Achieving financial freedom isn’t about winning the lottery or landing a six-figure salary overnight. For the vast majority of people, building real wealth is the result of consistent habits, smart choices, and a well-structured long-term plan.
Whether you are just starting your financial journey, trying to pay down debt, or looking to grow your investment portfolio, taking control of your money is one of the most rewarding decisions you can make.
In this comprehensive guide, we break down 15 actionable personal finance tips that stand the test of time.
These evergreen financial principles will help you manage your money, optimize your budget, eliminate bad debt, and build lasting wealth.
Part 1: Foundations of Smart Money Management
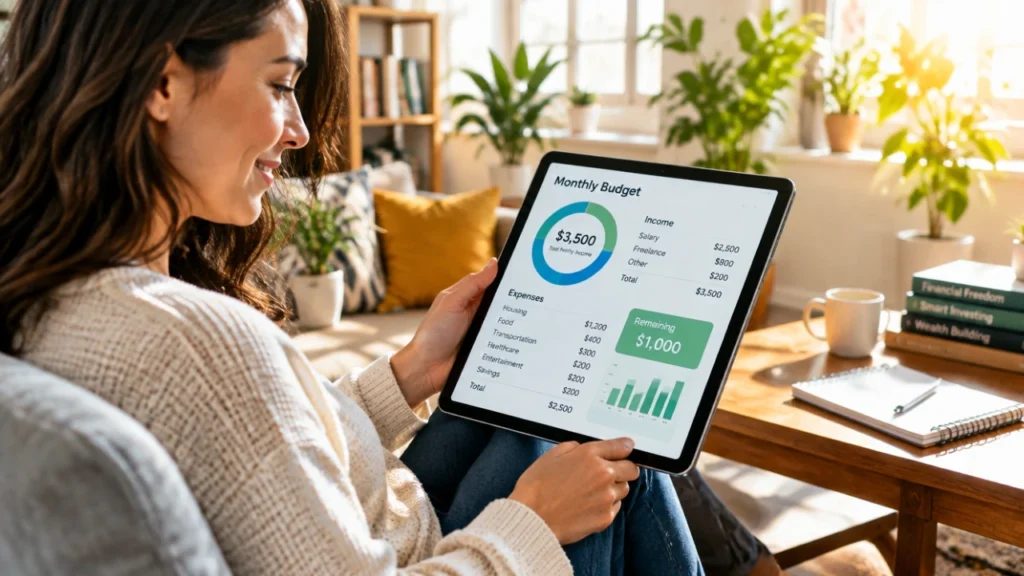
Before you can build a strong financial future, you need a solid foundation. Managing money effectively starts with understanding where your cash comes from and where it goes each month.
1. Follow a Budget Strategy That Fits Your Lifestyle
Budgeting is often misunderstood as restrictive. In reality, a budget doesn’t restrict your freedom—it gives you permission to spend intentionally. Without a clear budget, money tends to slip away through untracked impulse purchases and unused subscriptions.
There are several proven budgeting frameworks to choose from:
- The 50/30/20 Rule: Allocate 50% of your net income to Needs (housing, utilities, groceries), 30% to Wants (entertainment, dining out), and 20% to Savings & Debt Repayment.
- Zero-Based Budgeting: Give every single dollar a job before the month starts so that your income minus expenses equals zero.
- The Envelope System: Use physical cash or digital sub-accounts dedicated to specific categories to strictly limit spending.
Choose a system that feels natural to you. The best budget is not the most detailed one—it is the one you can consistently stick to month after month.
2. Build a Robust Emergency Fund
Life is unpredictable. Unplanned expenses—such as sudden medical bills, home repairs, or unexpected job loss—can easily ruin your financial plans if you are unprepared.
An emergency fund acts as a buffer between unexpected life events and high-interest debt:
- Aim to save 3 to 6 months’ worth of living expenses.
- Keep funds in a dedicated High-Yield Savings Account (HYSA).
- Separate emergency cash from your regular checking account to prevent impulse spending.
- Ensure liquidity so you can access money immediately when a real emergency strikes.
3. Track Every Single Expense for 30 Days
If you don’t know where your money goes, you cannot control where it goes. Many people underestimate their spending on minor daily habits like coffee runs, takeout meals, or recurring app subscriptions.
To gain full visibility over your finances:
- Track every single expense down to the cent for 30 days using an app, spreadsheet, or notebook.
- Categorize your spending into fixed and variable expenses.
- Identify non-essential spending leaks and reallocate those funds toward your long-term goals.
Part 2: Taming Debt and Controlling Expenses
Debt can be a helpful tool or a heavy financial burden depending on how you use it. High-interest consumer debt keeps you trapped in a cycle of paying for the past instead of investing in your future.
Debt Repayment Strategies Comparison
| Strategy | Primary Focus | Best For… | Key Benefit |
| Debt Snowball | Smallest balance first | Beginners needing fast wins | High psychological motivation |
| Debt Avalanche | Highest interest rate first | Analytical thinkers | Maximum mathematical savings |
4. Prioritize Eliminating High-Interest Debt
Not all debt is created equal. High-interest debt—especially credit card debt carrying 18% to 29% APR—is a financial emergency. The interest compounds rapidly, making it difficult to reduce the primary balance.
To eliminate high-interest debt effectively, focus on two main execution styles:
- The Debt Avalanche Method: Pay the minimum on all debts, but throw all extra money at the debt with the highest interest rate. Mathematically, this saves you the most money in interest over time.
- The Debt Snowball Method: Pay off the debt with the smallest balance first, regardless of the interest rate. This delivers quick psychological wins that keep you motivated to tackle larger balances.
5. Never Carry a Credit Card Balance Month-to-Month
Credit cards offer valuable benefits including cashback rewards, purchase protection, travel perks, and credit score building. However, these advantages are immediately wiped out if you pay credit card interest.
Key rules for healthy credit card usage:
- Only spend money you already have in your checking account.
- Set up automatic full balance payments every month.
- Never view your credit limit as available cash.
- Maintain low credit utilization to boost your credit score.
6. Audit and Cut Unnecessary Subscriptions
Subscription models are designed to make small recurring charges feel insignificant. Over time, streaming services, gym memberships, software trials, and monthly subscription boxes add up to hundreds of dollars a year.
Perform a simple quarterly audit:
- Review bank and credit card statements from the last three months.
- Identify every recurring service charge.
- Cancel any service you haven’t used in the past 30 days.
Part 3: Wealth Building and Investing Principles
Saving money is essential, but saving alone will not build long-term wealth. Inflation constantly erodes the purchasing power of cash over time. To grow your real net worth, you must invest strategically.
7. Start Investing Early to Harness Compound Interest
Compound interest occurs when your investment earnings generate their own earnings over time. The key driver of compound interest isn’t how much money you invest—it’s how early you start.
Investment Growth Comparison (Retirement at Age 65)
| Metric | Investor A (Starts at 25) | Investor B (Starts at 35) |
| Monthly Contribution | 300 | 300 |
| Years Investing | 40 Years | 30 Years |
| Total Out-of-Pocket Contribution | 144,000 | 108,000 |
| Estimated Balance at 65 (8% Return) | ~1,040,000 | ~440,000 |
Starting 10 years earlier yields more than double the final wealth due to time in the market.
8. Diversify Your Investments with Low-Cost Index Funds
Attempting to pick individual winning stocks is risky and demanding even for seasoned professional traders. For individual investors, diversification is the most reliable way to lower risk while capturing long-term market growth.
Broad-market index funds and Exchange-Traded Funds (ETFs) offer critical advantages:
- Instant Diversification: Spreads risk across hundreds or thousands of companies.
- Low Expense Ratios: Keeps management fees minimal so more of your returns remain invested.
- Consistent Returns: Tracks the overall historical growth of major stock markets.
9. Maximize Tax-Advantaged Retirement Accounts
Taking advantage of tax-sheltered accounts is one of the most effective ways to accelerate your wealth accumulation. Depending on local tax laws, take full advantage of key account types:
- Employer-Sponsored Accounts (e.g., 401(k)): Always contribute enough to claim the full employer match if available. This is effectively free money and an immediate 100% return on those funds.
- Individual Retirement Accounts (Traditional or Roth IRAs): Roth accounts allow your investments to grow completely tax-free, meaning zero income tax on qualified withdrawals in retirement.
- Health Savings Accounts (HSAs): Provide a triple-tax advantage: tax-deductible contributions, tax-free investment growth, and tax-free withdrawals for eligible medical costs.
10. Automate Your Finances (“Pay Yourself First”)
Human willpower is limited. Relying on self-discipline to manually transfer money into savings or investment accounts every month leaves room for emotional decisions and accidental spending.
Set up an automated financial workflow:
- Direct Deposit: Income lands in your primary checking account.
- Automatic Transfers: Scheduled investments and savings contributions move automatically on payday.
- Bill Payment: Fixed recurring monthly bills are automatically debited.
- Guilt-Free Spending: The remaining checking account balance is what you have left for everyday expenses.
Part 4: Smart Mindsets for Lasting Wealth
Financial management is as much about psychology as it is about mathematics. Developing healthy money habits and a long-term mindset helps protect you from poor impulsive decisions.
11. Practice Intentional Spending and Mindful Consumption
Living below your means doesn’t require living in frugal deprivation. Instead, it means spending intentionally on things that bring genuine value to your life while ruthlessly cutting back on things that don’t.
Useful rules of thumb for mindful consumption:
- The 72-Hour Rule: Wait 72 hours before completing any non-essential purchase to eliminate emotional impulse buying.
- Calculate Cost in Hours Worked: Divide the price of an item by your net hourly wage to understand its real cost in personal labor.
12. Avoid the Lifestyle Creep Trap
As your career progresses and your income grows, it is natural to want to upgrade your lifestyle—a nicer car, a bigger home, expensive meals, or luxury items. This phenomenon is known as Lifestyle Creep.
To prevent lifestyle inflation from eroding your wealth:
- Apply the 50/50 Rule to every raise, bonus, or windfall.
- Redirect 50% of the income increase directly into investments or debt payoff.
- Use the remaining 50% to upgrade your lifestyle or enjoy short-term purchases.
13. Protect Your Assets with Proper Insurance Coverage
Building wealth takes years, but a single major accident or lawsuit can wipe out your hard-earned assets if you are uninsured or underinsured.
Essential insurance policies to consider:
- Health Insurance: Protects against catastrophic medical costs.
- Auto and Home/Renters Insurance: Protects key assets and covers personal liability.
- Disability Insurance: Replaces your income if an illness or injury prevents you from working.
- Term Life Insurance: Provides financial support to dependents if you pass away during your working years.
14. Invest in Your Earning Potential
While cutting expenses can save you money, there is a limit to how much you can cut. There is no upper limit to how much you can earn.
Key ways to boost your income capacity:
- Learn high-demand technical, strategic, or communication skills.
- Earn industry-recognized professional certifications.
- Practice negotiation tactics for salary reviews and job offers.
- Build scalable secondary income streams or freelance services.
15. Schedule Regular Financial Check-Ins
Your personal finances are not something you set up once and forget forever. Your goals, income level, and life circumstances evolve, and your financial strategy must adapt along with them.
Recommended review schedule:
- Monthly Review (15–30 mins): Review overall spending, verify credit statements, and set targets for the next month.
- Quarterly Review (1 hour): Check emergency fund balances, track net worth growth, and evaluate savings milestones.
- Annual Review (2 hours): Rebalance investment allocations, audit insurance coverage, organize tax planning, and set fresh annual targets.
Final Thoughts: The Journey to Financial Independence
Building personal wealth isn’t about rapid gains or complex shortcuts. It is about committing to proven, simple habits over a sustained period of time.
To get started right away, focus on these three priorities:
- Build a basic emergency cushion.
- Eliminate high-interest credit card debt.
- Set up automated monthly investment transfers.
By taking proactive control of your money today, you build real peace of mind and long-term financial security for tomorrow.
Frequently Asked Questions (FAQ)
How much money should I save every month?
A popular benchmark is saving at least 20% of your net take-home pay. If 20% feels unachievable right now, start with 5% or 10% and increase your savings rate gradually as your income grows or expenses shrink.
Should I pay off debt or invest first?
Focus on paying off high-interest debt (such as credit cards carrying rates over 8–10%) before investing heavily. However, if your employer offers a retirement contribution match, always contribute enough to claim the full match first—it offers an immediate, guaranteed return.
Where is the safest place to keep my emergency fund?
A High-Yield Savings Account (HYSA) is an ideal location for an emergency fund. It keeps your cash liquid and safe while offering significantly higher interest rates than traditional checking or standard savings accounts.